Taiwan stock investment focuses on the top 10% of companies, economic momentum rebounds from a low base
Benefiting from a rebound in economic momentum from a low base, Taiwan stock investment focuses on the top 10% of companies
Fubon recently held a financial trend forum, analyzing 2017 views on stock market investment across the three regions of Taiwan, China, Hong Kong, China and Mainland China, emphasizing that priority can be given to those that saw larger declines in 2016, while also considering markets with smaller cumulative gains since the financial crisis and still-low price-to-earnings ratios.
At present, weak global demand and intensifying competition from the red supply chain have reduced the contribution of foreign trade surpluses, causing Taiwan's economy to show low growth in recent years. From a low base, Taiwan's economic growth rate in 2017 has a chance to rebound upward to 1.5%.
In recent years, China has maintained a 6%-7% economic growth rate, continuing to drive the expansion of its economic scale. In 2015, China's economic growth rate accounted for 15% of the global economy, and in 2016 it is expected to surpass the eurozone, ranking second only to the United States, with its importance growing by the day. As China becomes the world's largest exporter, the international status of the renminbi has risen. On October 1, it was officially included among the International Monetary Fund's Special Drawing Rights (SDR) reserve currencies, alongside the US dollar, euro, pound sterling and Japanese yen, with a share of 10.9%, which will accelerate the pace of renminbi internationalization in the future.
Since China began promoting the 12th Five-Year Plan in 2011, the share of domestic-demand service industries in China's overall GDP has become comparable to that of manufacturing, and in 2015 its share exceeded 50%. The 13th Five-Year Plan will still continue the adjustment of the economic structure; in addition, in recent years China has started opening its capital market, with foreign capital inflows growing exponentially. Since 2005, QFII has been opened, with investment quota growing from 46.6 billion yuan to 504.8 billion yuan in 2015, an 11-fold increase; since 2015, RQFII has been opened, with investment quota growing from 67 billion yuan to 444.3 billion yuan in 2015, a 7-fold increase.
According to data cited by Fubon, over the past 10 years, the trends of China's stock market and housing prices have gone from moving in the same direction, to decoupling, to recently showing an inverse relationship, mainly because the scale of both the stock market and the housing market has increased greatly. As mainland housing prices hit new highs and lead to absurd social incidents, it is estimated that the government's efforts to curb housing speculation will begin to strengthen next year, and funds invested in the housing market will exit and flow into the stock market. The reason is that the current price-to-book ratio (PBR) of the Shanghai Composite Index is only 1.7 times, far below its historical average, showing that the current valuation of the stock market is severely undervalued, and the attractiveness of stock market investment is rising.
Driven by the continued rise in the international status of the renminbi, the opening of China's capital market, the inflow of funds from the government's housing crackdown, and policy benefits such as the launch of Shenzhen-Hong Kong Stock Connect, the price-to-book ratio (PBR) of the Shanghai Composite Index in 2017 is expected to be 1.7-2.3 times, with a range of 3000-4200 points. For the 2017 investment allocation in mainland stocks, Fubon Securities Investment Consulting proposed focusing on the three major SHOP investment trends, including the 13th Five-Year Plan (Planning), One Belt One Road (OB&OR), and Shenzhen-Hong Kong Stock Connect (SZ-HK Connect).
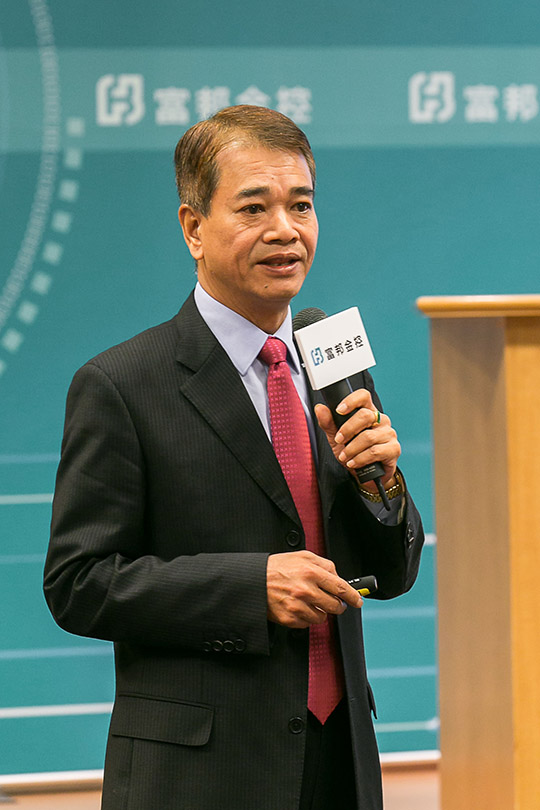
▲Fubon Securities Investment Consulting General Manager Xiao Qianxiang gave the keynote on Greater China stock market investment strategy at the press conference for the "2017 Fubon Financial Trend Forum," and also provided the three major VIP stock selection directions for Taiwan stocks in 2017 under corporate focus.